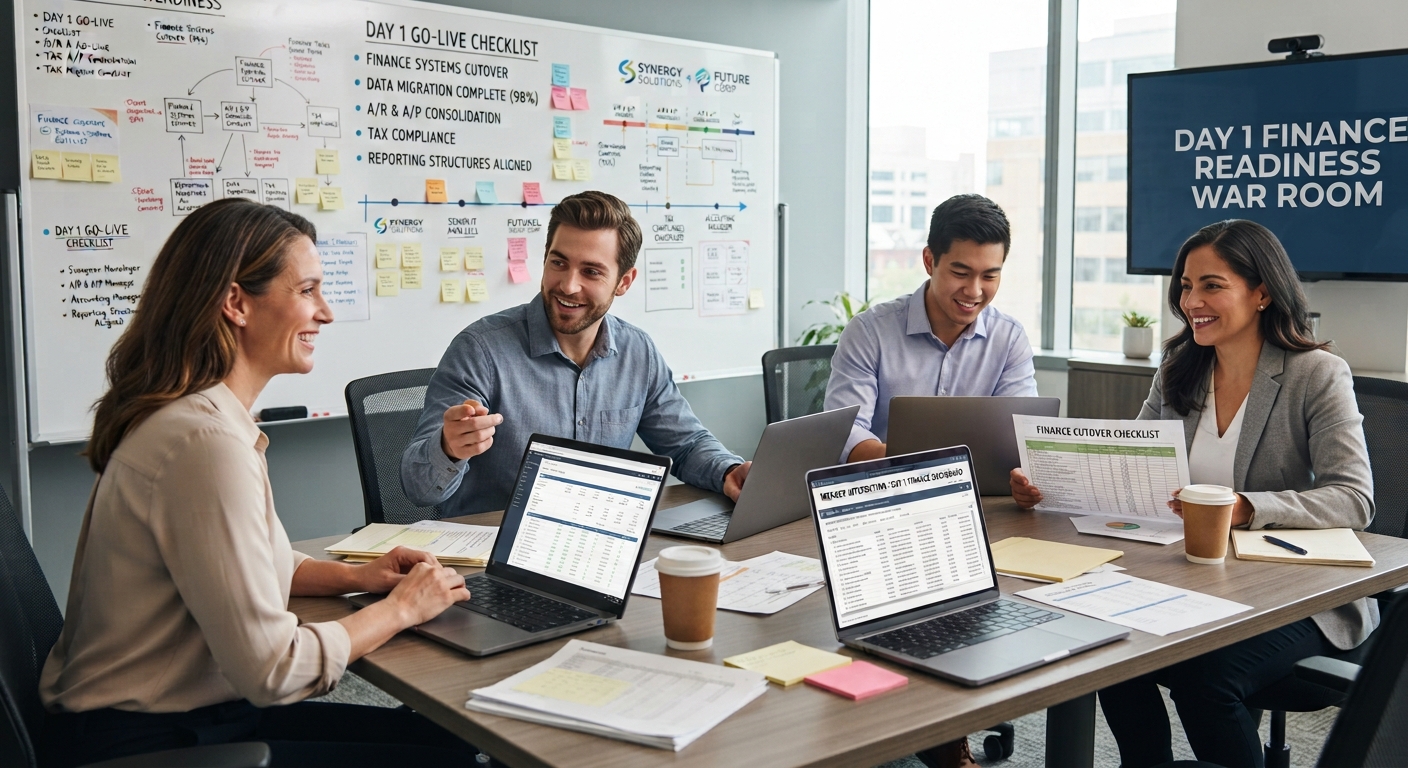
A case: the deal closes on Monday, and on Monday someone has to be able to pay the suppliers
THE SHORT VERSION
Two companies are combining. The technology integration team is planning systems, access and cut-over. For finance, the same programme decides whether, on Legal Day 1, the combined business can pay suppliers, run payroll, record transactions and report.
The work runs in a fixed order: assess both environments, define what must work on Day 1, identify gaps and risks, set up governance, run the programme, and keep integrating after closing.
Finance also owns one part nobody else does: controlling the integration budget and timeline, and classifying integration costs correctly.
Day 1 finance readiness is the part of a technology integration programme that finance cannot delegate. Systems teams can make a ledger available. Only finance can confirm that the right people can approve payments, that the cut-off is clean, and that the first week’s transactions will land in the right entity. This case follows a common situation: a merger with a technology integration programme running across both firms, from assessment and Legal Day 1 through post-close integration, seen from the finance side. The case is representative, not a named company, and it is the type of situation NEO Expertise supports finance teams through.
On this page
- The situation
- Step 1: Assess both environments
- Step 2: Define what must work on Legal Day 1
- Step 3: Gaps, risks and governance
- Step 4: Run the programme across both firms
- Step 5: Post-close integration and budget control
- Where Day 1 goes wrong for finance
- Day 1 Finance Readiness Checklist
- Frequently asked questions
The Situation
Two professional services firms have agreed to combine. The acquiring firm will absorb the other’s business into its legal structure on the closing date, Legal Day 1. A technology integration programme has been set up to plan systems, access and data migration, with workstreams for infrastructure, applications, security and data.
Finance’s systems (the general ledger, payables, receivables, payroll, banking and reporting) sit inside those workstreams, but the programme plan describes them as applications to migrate, not as processes that must keep working. Finance joins the programme to make sure the business can operate on Day 1, not just log in.
Step 1: Assess Both Environments
The technology assessment covered both firms’ environments. Finance added its own layer: for every finance process, which system runs it at each firm, who operates it, and what changes on Legal Day 1.
The most important finding was not a system. It was a list of people. At the acquired firm, three individuals held the bank payment approval rights, and one of them was leaving at closing. No new signatories had been added, and the bank’s onboarding of new signatories required identity and ownership checks. Banks apply customer due diligence under the EU’s Anti-Money Laundering Directive (EU) 2015/849, and changing mandates for a newly acquired entity routinely takes several weeks.
Step 2: Define What Must Work on Legal Day 1
Legal Day 1 readiness was defined as a short list of finance capabilities that must work on the first morning, each with an owner, a test and a fallback. Illustrative Day 1 finance readiness list from this case:
| Capability | Owner | Tested by | Fallback if not ready |
|---|---|---|---|
| Supplier payment release | Treasury | Test payment of €1 per bank | Existing signatories under interim authority |
| Payroll run for all employees | Payroll lead | Parallel run of prior month | Previous provider for one more cycle |
| Ledger posting in the correct entity | Financial Controller | Test journals in each entity | Suspense account with daily clearance |
| Customer invoicing with new details | Receivables lead | Sample invoices reviewed | Old template with covering notice |
| Cut-off at closing date | Financial Controller | Cut-off checklist signed | None: must be ready |
| Day 1 cash and flash reporting | FP&A | Dry run on prior week | Manual bank balance report |
The fallback column did most of the work. When a capability could not be guaranteed, the fallback was agreed in advance rather than improvised on the day. Only one item had no fallback: the cut-off. Transactions before and after closing belong to different owners, and a messy cut-off contaminates the opening balance sheet.
Unresolved issues were identified before closing and either fixed or accepted explicitly by the steering committee.
Step 3: Gaps, Risks and Governance
The gap and requirements analysis gathered business and technical requirements for each finance process and developed remediation recommendations. Integration risks were assessed for potential impact, mitigation actions were defined, and critical risks were escalated.
Governance defined roles and responsibilities, the decision-making structure and the escalation route. For finance, one rule mattered most: no change to a system that feeds the ledger in the two weeks either side of a month end, unless the Controller agreed. That single rule prevented the programme’s cut-over dates from colliding with the close.
Step 4: Run the Programme Across Both Firms
Programme management tracked tasks, deadlines, issues, dependencies and priorities across the workstreams. Teams from both firms were coordinated through joint working sessions, with communication and priorities agreed across the two organisations.
Finance ran its own workstream inside the programme, with defined activities and owners: bank mandates, payroll migration, chart of accounts mapping, customer and supplier master data, and reporting. Progress was tracked alongside the technology workstreams, because every finance milestone depended on a technology one.
Payroll showed why. The parallel run of the prior month on the acquiring firm’s payroll system produced net pay differences for 41 of 380 employees. These figures are illustrative. Most traced to allowances configured as taxable in one system and non-taxable in the other, and a handful to pension contribution rates that had not been migrated. Each difference was resolved and the parallel run repeated. Because the second run was still not clean two weeks before closing, the fallback (one more cycle on the old provider) was triggered deliberately, not on the day.
Master data followed the same pattern. Customer and supplier records were frozen for new additions five working days before closing, migrated, and reconciled record by record, so that no invoice raised in the first week carried the old entity’s bank details. The reporting milestones followed the approach in preparing subsidiaries for group reporting.
Step 5: Post-Close Integration and Budget Control
Legal Day 1 was a milestone, not the finish. After closing, integration continued: remaining migrations, outstanding technology issues, and the move from fallbacks to permanent processes. Standard integration frameworks, tracking tools and documented processes were kept for the next deal.
Finance owned budget and timeline control. Illustrative: the integration budget was €4.5 million. Four months after closing, €3.1 million was committed and €2.4 million spent, but the forecast to complete stood at €5.2 million, an overrun of €0.7 million driven mainly by extending the previous payroll provider for two extra cycles. Reporting the forecast, not just the spend, gave the steering committee time to act.
Classification mattered too. Under IFRS 3, as endorsed in the EU in Regulation (EC) No 1126/2008, acquisition-related costs are expensed as incurred rather than added to the cost of the acquisition, so integration and deal costs were tagged by nature from the first invoice to keep reporting and any adjusted results clean.
The finance questions for the first weeks after closing are set out in what a CFO should review immediately after an acquisition, and the full sequence in the first 100 days finance integration roadmap.
Where Day 1 Goes Wrong for Finance
- Bank mandates left to the last week. Signatory changes need bank due diligence and take weeks, not days.
- Systems ready, processes not. A ledger that is available but has no correct entity structure produces a month of misposted transactions.
- No fallback plan. Improvising a payroll workaround on the morning of Day 1 is how employees go unpaid.
- Tracking spend instead of forecast. By the time actual spend shows an overrun, it is too late to prevent it.
This approach assumes a single legal closing date. In a staggered closing, where entities in different countries complete on different dates, each country has its own Day 1, and the readiness list has to be repeated country by country with its own local banks and payroll.
The Day 1 Finance Readiness Checklist
Use this as a working checklist. Each item is a check to complete, not a topic to consider.
Before closing
- ☐ Start bank mandate and signatory changes as early as signing allows
- ☐ Map every finance process to its system at both firms
- ☐ Run a payroll parallel run and resolve every difference
- ☐ Freeze, migrate and reconcile customer and supplier master data
- ☐ Agree and sign off the cut-off checklist
Day 1 capabilities
- ☐ Release a test payment through each bank
- ☐ Confirm payroll can run for all employees
- ☐ Post test journals in each legal entity
- ☐ Check invoices carry the correct entity and bank details
- ☐ Produce the first cash and flash report
Fallbacks and governance
- ☐ Agree a written fallback for every capability except the cut-off
- ☐ Allow no change to systems feeding the ledger around month end
- ☐ Agree the escalation route and decision rights before Day 1
After closing
- ☐ Move from fallbacks to permanent processes
- ☐ Track integration spend, commitments and forecast to completion
- ☐ Tag acquisition-related and integration costs by nature from the first invoice
Frequently Asked Questions
What does Day 1 finance readiness mean?
It means the combined business can perform its essential finance processes on the first day after legal closing: release supplier payments, run payroll, post transactions to the correct entity, invoice customers with correct details, apply a clean cut-off, and report the day’s cash position. Each capability needs an owner, a test and a fallback.
Why do bank mandates delay Day 1 readiness?
Adding or changing signatories requires the bank to complete customer due diligence on the new owners and authorised persons, which can take several weeks. Start mandate changes as soon as signing allows, and agree an interim authority for existing signatories as a fallback.
How should integration costs be accounted for after an acquisition?
Under IFRS 3, acquisition-related costs are expensed as incurred, not added to the acquisition cost. Tag deal and integration costs by nature from the first invoice, track them against budget and forecast to completion, and keep them identifiable for any adjusted results.
NEXT STEP
NEO Expertise supports finance teams through Day 1 and the months after it, adding capacity for cut-off, opening balances, reconciliations and integration budget tracking. You can discuss your finance integration project with our team.
Brahim Rami | Member of institute of chartered accountants in Morocco
He is a CPA and tax advisor, founder of NeoExpertise.net, a Legal and Tax firm helping foreign companies with business setup, due diligence, payroll, and tax compliance in Morocco and Africa.