A case: a private equity investor arrives, and the finance function has to change while it keeps running
THE SHORT VERSION
A private equity firm takes a minority stake in a founder-led company. The investment case depends on growth, and growth depends on a finance function that can produce reliable numbers, faster, at a larger scale.
The finance and accounting team is small and fully occupied with day-to-day operations. It has no time to assess itself, select new systems, run capital projects and keep the books closed at the same time.
The work: assess the function, fix accounting weaknesses, define system requirements, build a prioritised plan, add accounting capacity, and keep the business running throughout.
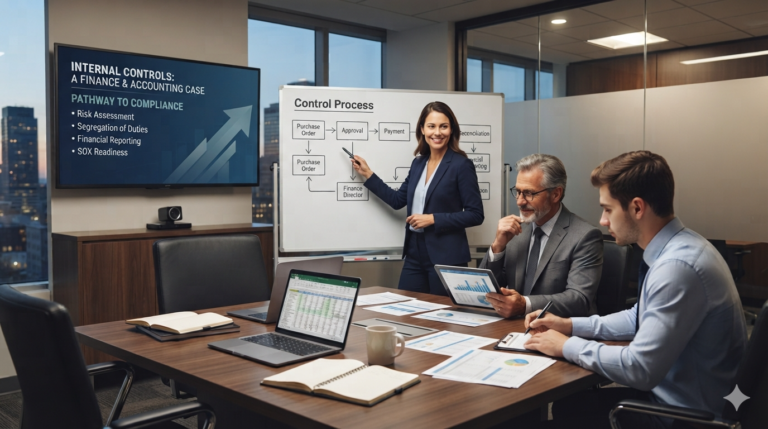
Finance transformation after private equity acquisition rarely starts as a planned project. It usually starts with a gap between what the new investor expects and what the finance team can produce. This case follows a common version of that situation: a PE firm acquires a minority stake, the board asks for monthly reporting, a systems roadmap and control over capital spending, and the existing team is already at capacity. It sets out the order in which the finance work was done, from the post-deal assessment through accounting fixes, system selection, transformation planning and capital projects, to the extra capacity that kept daily operations stable. The case is representative, not a named company, and it is the type of situation NEO Expertise supports finance teams through.
On this page
- The situation
- Step 1: The post-deal finance assessment
- Step 2: Fixing the accounting foundations
- Step 3: Finance systems requirements
- Step 4: The transformation plan and capital projects
- Step 5: Adding capacity without disrupting operations
- Where PE-backed transformations stall
- Post-Investment Finance Checklist
- Frequently asked questions
The Situation
The company is profitable and growing, run by its founders, with a finance team of six people covering general accounting, payables, receivables and payroll. Reporting to the founders has been quarterly and informal. The new investor holds a minority stake with board seats and information rights.
Within weeks of completion, the board asks for three things: monthly management accounts within ten working days, a view on whether the accounting system can support the growth plan, and a structured process for approving and tracking capital projects. Each request is reasonable. Together, they are more than the current team can absorb while keeping the daily finance operations running.
Step 1: The Post-Deal Finance Assessment
The work began with a current-state assessment of the finance and accounting organisation: who does what, which capabilities exist, and where the gaps and risks sit. The assessment was built from the ledger and the close file, not from interviews alone. Interviews describe how the process is meant to work. The close file shows how it does.
The assessment produced four lists: finance gaps, accounting gaps, operational risks and inefficiencies, each with an owner and a priority. The same questions a CFO asks after a full acquisition apply here, as set out in what a CFO should review immediately after an acquisition, with one difference: in a minority deal, the founders still run the business, so every change needs their agreement.
Step 2: Fixing the Accounting Foundations
The accounting review covered general accounting, account reconciliations, intercompany accounting, fixed assets, financial processes and reporting. Three areas needed immediate work:
- Reconciliations. Bank accounts were reconciled monthly, but most other balance sheet accounts only at year end, for the auditor.
- Intercompany. Two operating entities traded with each other, and the balances had not agreed for several quarters. The approach in reconciling intercompany balances resolved the differences and set a monthly matching routine.
- Fixed assets. The register had not been reviewed in years.
Illustrative figures. The fixed asset register held 3,400 lines. The review found 410 fully depreciated assets still in use with no review of useful lives, 95 assets that could not be located, and €0.9 million in assets under construction for more than 12 months that had never been transferred to the right category or started depreciating. Under IAS 16, as endorsed in the EU in Regulation (EC) No 1126/2008, depreciation begins when an asset is available for use, so the unstarted depreciation was a real misstatement, not a housekeeping point.
Step 3: Finance Systems Requirements
The accounting system had been chosen when the company was a third of its current size. The systems workstream assessed it against the growth plan and identified the gaps: no multi-entity consolidation, manual month-end journals, and budgeting done entirely in spreadsheets.
Finance then defined its requirements for an enterprise resource planning (ERP) system and an enterprise performance management (EPM) tool for budgeting, forecasting and consolidation. The requirements went into a request for information to a long list of vendors, then a request for proposal to a short list, followed by a structured evaluation and a recommendation to the board.
The requirements came from the finance processes, not from vendor demonstrations. Each requirement traced back to a specific step in the close, the reporting pack or the budget cycle that the current system could not support.
Step 4: The Transformation Plan and Capital Projects
The assessment, accounting fixes and systems work were combined into one plan: current state, future state, a prioritised list of initiatives, timelines, named owners and a tracker reviewed monthly by the CFO and the board.
Capital projects needed their own discipline. The investor wanted every project above a threshold approved against a business case and tracked against budget. Finance reviewed the existing project portfolio, set priorities, and built a tracking routine.
Illustrative capital project prioritisation.
| Project | Budget (€m) | Spent to date (€m) | Business case | Priority |
|---|---|---|---|---|
| New production line | 2.40 | 0.60 | Approved, capacity for growth plan | 1 |
| Warehouse extension | 1.10 | 0.85 | Approved, 77% spent, overrun risk | 2 |
| ERP replacement | 0.75 | 0.00 | Pending system selection | 3 |
| Office refurbishment | 0.30 | 0.05 | No business case | Paused |
The table forced one useful conversation early: the warehouse extension had spent 77% of its budget with work outstanding, and nobody had reported it because nobody had been asked to.
Step 5: Adding Capacity Without Disrupting Operations
None of this could come out of the existing team’s time without the monthly close slipping. The answer was additional accounting capacity: experienced support for general accounting, fixed assets, intercompany and reconciliations, with advisory oversight of the transformation plan, while the permanent team kept the day-to-day finance operations running.
Business continuity was treated as a deliverable in its own right. Critical finance activities (payroll, supplier payments, the close, tax filings) were monitored weekly, and the PE team and the founders were kept aligned through one shared tracker rather than separate requests.
The end state was growth readiness: standardised processes, a selected system, stronger accounting operations, better reporting and a finance organisation that can support the next stage. For investors planning further acquisitions, the finance integration approach for buy-and-build strategies builds on the same foundations, and the first 100 days finance integration roadmap sets out the sequence for the first months after a deal.
Where PE-Backed Transformations Stall
- Buying the system before fixing the process. A new ERP loaded with unreconciled balances and undocumented processes reproduces the old problems faster.
- Asking the existing team to do everything. The close slips first, then the investor’s confidence in the numbers.
- Separate requests from investor and founders. Two sets of priorities with no shared tracker leave finance deciding between its shareholders.
- Monthly reporting built on quarterly foundations. Producing management accounts every month from a ledger that is only reconciled at year end means publishing estimates. The reconciliation routine has to move to monthly before the reporting pack does, or the board will start questioning figures that change after they are presented.
This approach assumes the investor has information rights and board influence. In a small minority stake without them, finance transformation depends entirely on the founders’ agreement, and the plan should be scaled down to what they will sponsor.
The Post-Investment Finance Checklist
Use this as a working checklist. Each item is a check to complete, not a topic to consider.
Assessment
- ☐ Review the finance and accounting organisation from the ledger and close file
- ☐ List finance gaps, accounting gaps, operational risks and inefficiencies
- ☐ Agree priorities with both the founders and the investor
Accounting foundations
- ☐ Move balance sheet reconciliations from year end to monthly
- ☐ Match intercompany balances every month
- ☐ Review the fixed asset register, useful lives and missing assets
- ☐ Check that assets under construction are transferred and depreciation has started
Systems
- ☐ Assess the current system against the growth plan
- ☐ Write requirements from documented finance processes, not vendor demonstrations
- ☐ Run a request for information, then a request for proposal and a structured evaluation
Plan, capital projects and capacity
- ☐ Build one prioritised plan with owners, timelines and a monthly tracker
- ☐ Require a business case for every capital project above the threshold
- ☐ Track spend and commitments against budget per project
- ☐ Add accounting capacity so the monthly close does not slip
- ☐ Monitor payroll, supplier payments, the close and tax filings weekly
Frequently Asked Questions
What does finance transformation after a private equity acquisition involve?
It typically covers a current-state assessment of finance and accounting, fixing weaknesses in reconciliations, intercompany and fixed assets, defining system requirements, a prioritised transformation plan with owners, capital project controls, and additional capacity so daily finance operations continue while the changes are made.
Should the ERP be selected before or after fixing the accounting?
Fix the core accounting first, or at least in parallel. Requirements should come from documented finance processes, and migration needs reconciled opening balances. Selecting a system before the process is understood usually means configuring it around workarounds that should have been removed.
Why does a PE-backed finance team need additional capacity?
Because the investor’s reporting, systems and capital project requests arrive on top of the existing workload. Additional accounting capacity lets the permanent team keep the close, payments and payroll running while the transformation work is delivered, and it avoids burning out the people the business depends on.
NEXT STEP
NEO Expertise supports finance teams through post-investment transformation, adding accounting capacity for reconciliations, fixed assets, intercompany and reporting while your team keeps daily operations running. You can discuss your finance project with our team.
Brahim Rami | Member of institute of chartered accountants in Morocco
He is a CPA and tax advisor, founder of NeoExpertise.net, a Legal and Tax firm helping foreign companies with business setup, due diligence, payroll, and tax compliance in Morocco and Africa.