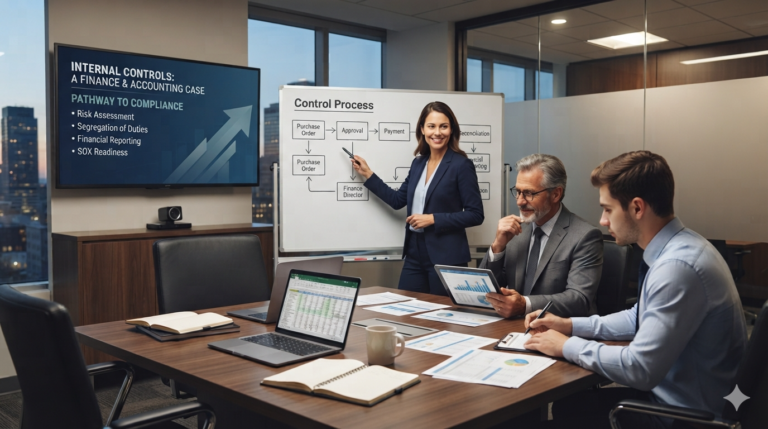
Internal Controls for a Newly Public Company: A Finance and Accounting Case
What internal controls a newly public company needs first: journal entry segregation, evidenced reconciliations, tiered approvals and written procedures.
What internal controls a newly public company needs first: journal entry segregation, evidenced reconciliations, tiered approvals and written procedures.
The reusable artefacts that let a serial acquirer integrate the tenth company as fast as…
When acquisition is the operating model, finance integration stops being a project and becomes a…
What has to be true before a newly acquired company can submit into the group…